$6 billion in 30 days
Frontier labs stopped trying to sell models directly, and split into two structures for deploying them.
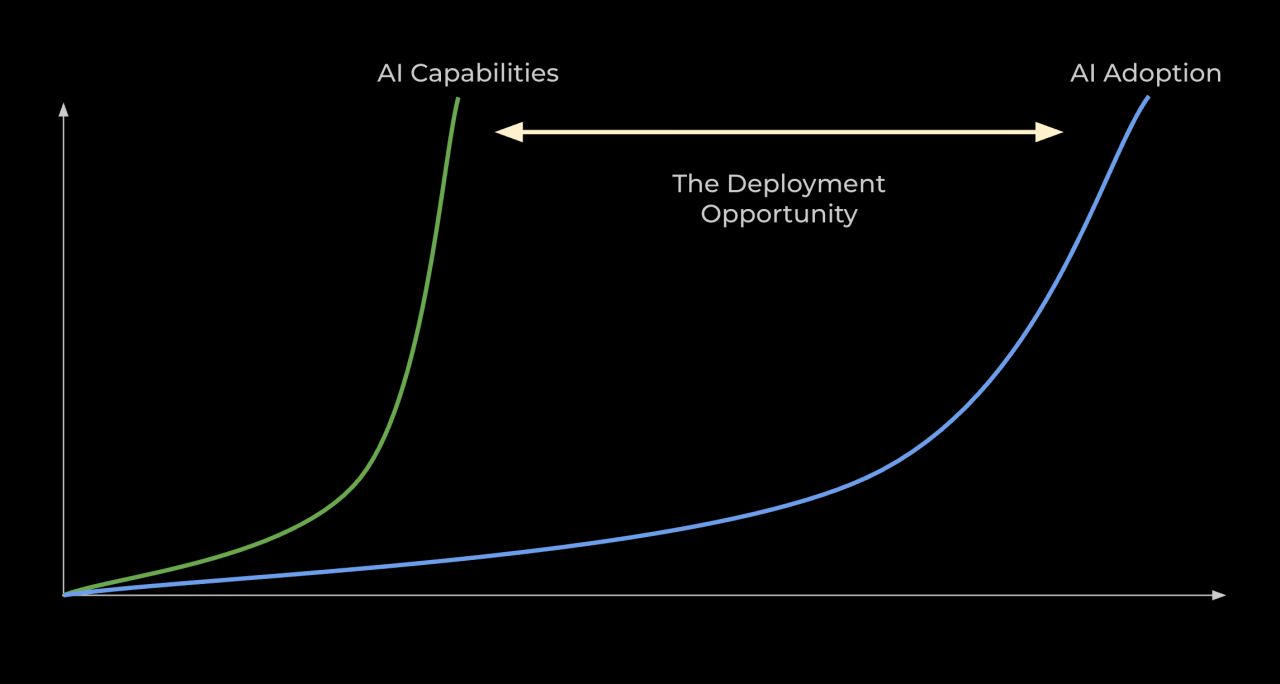
$6 billion in 30 days. Frontier labs just stopped trying to 'direct sell' models to enterprises.
April 21. Microsoft launches its Frontier Transformation partner program. Sits on top of Avanade, the JV they started with Accenture in 2000 to implement Windows in enterprises.
April 22. Google commits $750M to its consulting partner ecosystem. Embeds engineers alongside Accenture, Capgemini, Deloitte. Strikes deals with CVC and Vista.
May 4. Anthropic launches a $1.5B AI services firm with Blackstone, Hellman & Friedman, and Goldman Sachs.
May 11. OpenAI launches The Deployment Company at a $10B valuation with TPG, Brookfield, Advent, and Bain Capital. Acquires Tomoro and 150 forward-deployed engineers from day one.
Same problem. Two structures.
Google and Microsoft are betting horizontal. Finance the existing consulting ecosystem. Let the SIs do the work. License the model.
OpenAI and Anthropic are betting vertical. Build your own consulting arm. Acquire engineers. Distribute through PE portfolios.
We've seen this movie before. Microsoft and Accenture launched Avanade in 2000 to put Windows inside enterprises. It is still operating today. This approach is not new, it's 25 years old. The product is just different.
The consistent theme of the last 30 days is that everyone seems to agree the bottleneck is institutional change, not actually capability. The model might be the product, but the deployment is the business.
Two questions I am left pondering:
Will the vertical model actually scale, or does it cap at Palantir's customer count?
Will the horizontal model actually work for AI, or does it dilute model differentiation into a partner credentials race?
First posted on LinkedIn.